Added to cart
 Psychology Tools · Psychology
1,200 of damage. A 500 excess. So the claim pays 700. The premium is 1,150 a year and a claim puts it up by half for the first year, working back over four. That comes to 1,438. Claiming leaves you 738 worse off than not claiming, and the damage would have to be worth 1,938 […]
Download link by email · valid 30 days
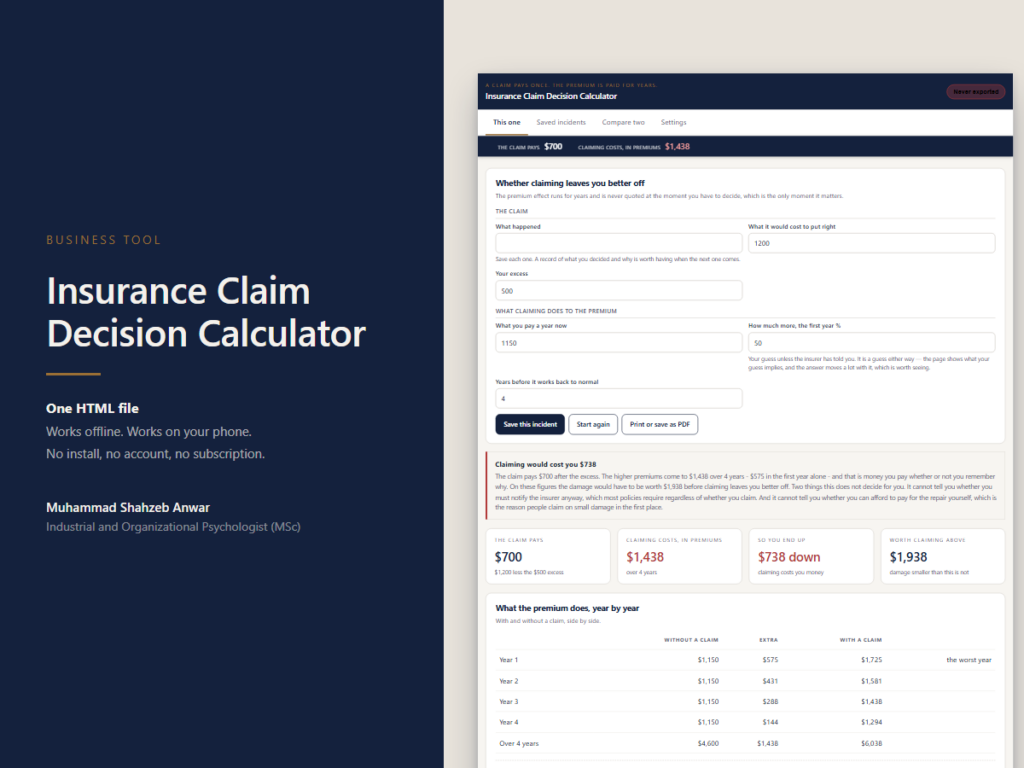
1,200 of damage. A 500 excess. So the claim pays 700.
The premium is 1,150 a year and a claim puts it up by half for the first year, working back over four. That comes to 1,438. Claiming leaves you 738 worse off than not claiming, and the damage would have to be worth 1,938 before it was worth making a claim at all.
That comparison is never in front of you at the moment you have to decide. The claim pays once and you notice it. The higher premium is paid every year until it works back, by which time nobody connects it to the thing that happened.
The page shows the premium year by year, with and without a claim, side by side, and gives you the threshold to keep for next time.
It says when a claim IS worth making, which is most of the time for anything substantial. This is not an argument against claiming — it is an argument against claiming on small damage without doing the sum.
Two things it deliberately does not decide. Not claiming is not the same as not telling: most policies require you to notify an incident whether or not you claim on it, and this page has no view on your policy and no view on the law. And it does not know whether you can afford to pay for the repair yourself, which is the actual reason people claim on small damage and is a perfectly good one that no arithmetic overrides.
The loading and the number of years are estimates unless your insurer has given you the figures. The answer moves a great deal with them, which is a reason to try a worse guess and see whether it changes, not a reason to skip the sum.
Save as many versions as you like and put any two side by side, figure against figure, with the better one on each line marked and the difference in its own column. That screen is the one that decides things, and it is the part a free calculator cannot do at all. Save each incident and the threshold stops being something you have to remember.
One HTML file. No account, no subscription, no internet needed. Opens on Windows, Mac and Android; the readme explains the extra step on iPhone and iPad, where Apple blocks JavaScript in downloaded files and every tool of this kind is affected.
Everything lives in your browser on your device. Nothing is uploaded, which is why it works offline and why nobody else can see your figures — and it also means clearing your browsing data deletes it. The tool does not pretend otherwise: the header shows how long since your last export at all times, turns amber after three days and red after seven, and export is one click that produces a plain file you keep.
Please verify the product description for exact OS compatibility, but the vast majority of our web-based tools and digital utilities operate beautifully on any operating system.
No, this is a strict one-time purchase that unlocks lifetime access, including all future software updates and feature rollouts.
Post-purchase, you will receive an instant download link securely delivered to your email, alongside your activation license key if applicable.
We include rigorous, detailed documentation, and our responsive support team is on standby to assist you with any installation or configuration hurdles.
Added to cart
Your cart is empty
Browse Shop Tools & Software · Tool
 Tools & Software · Tool